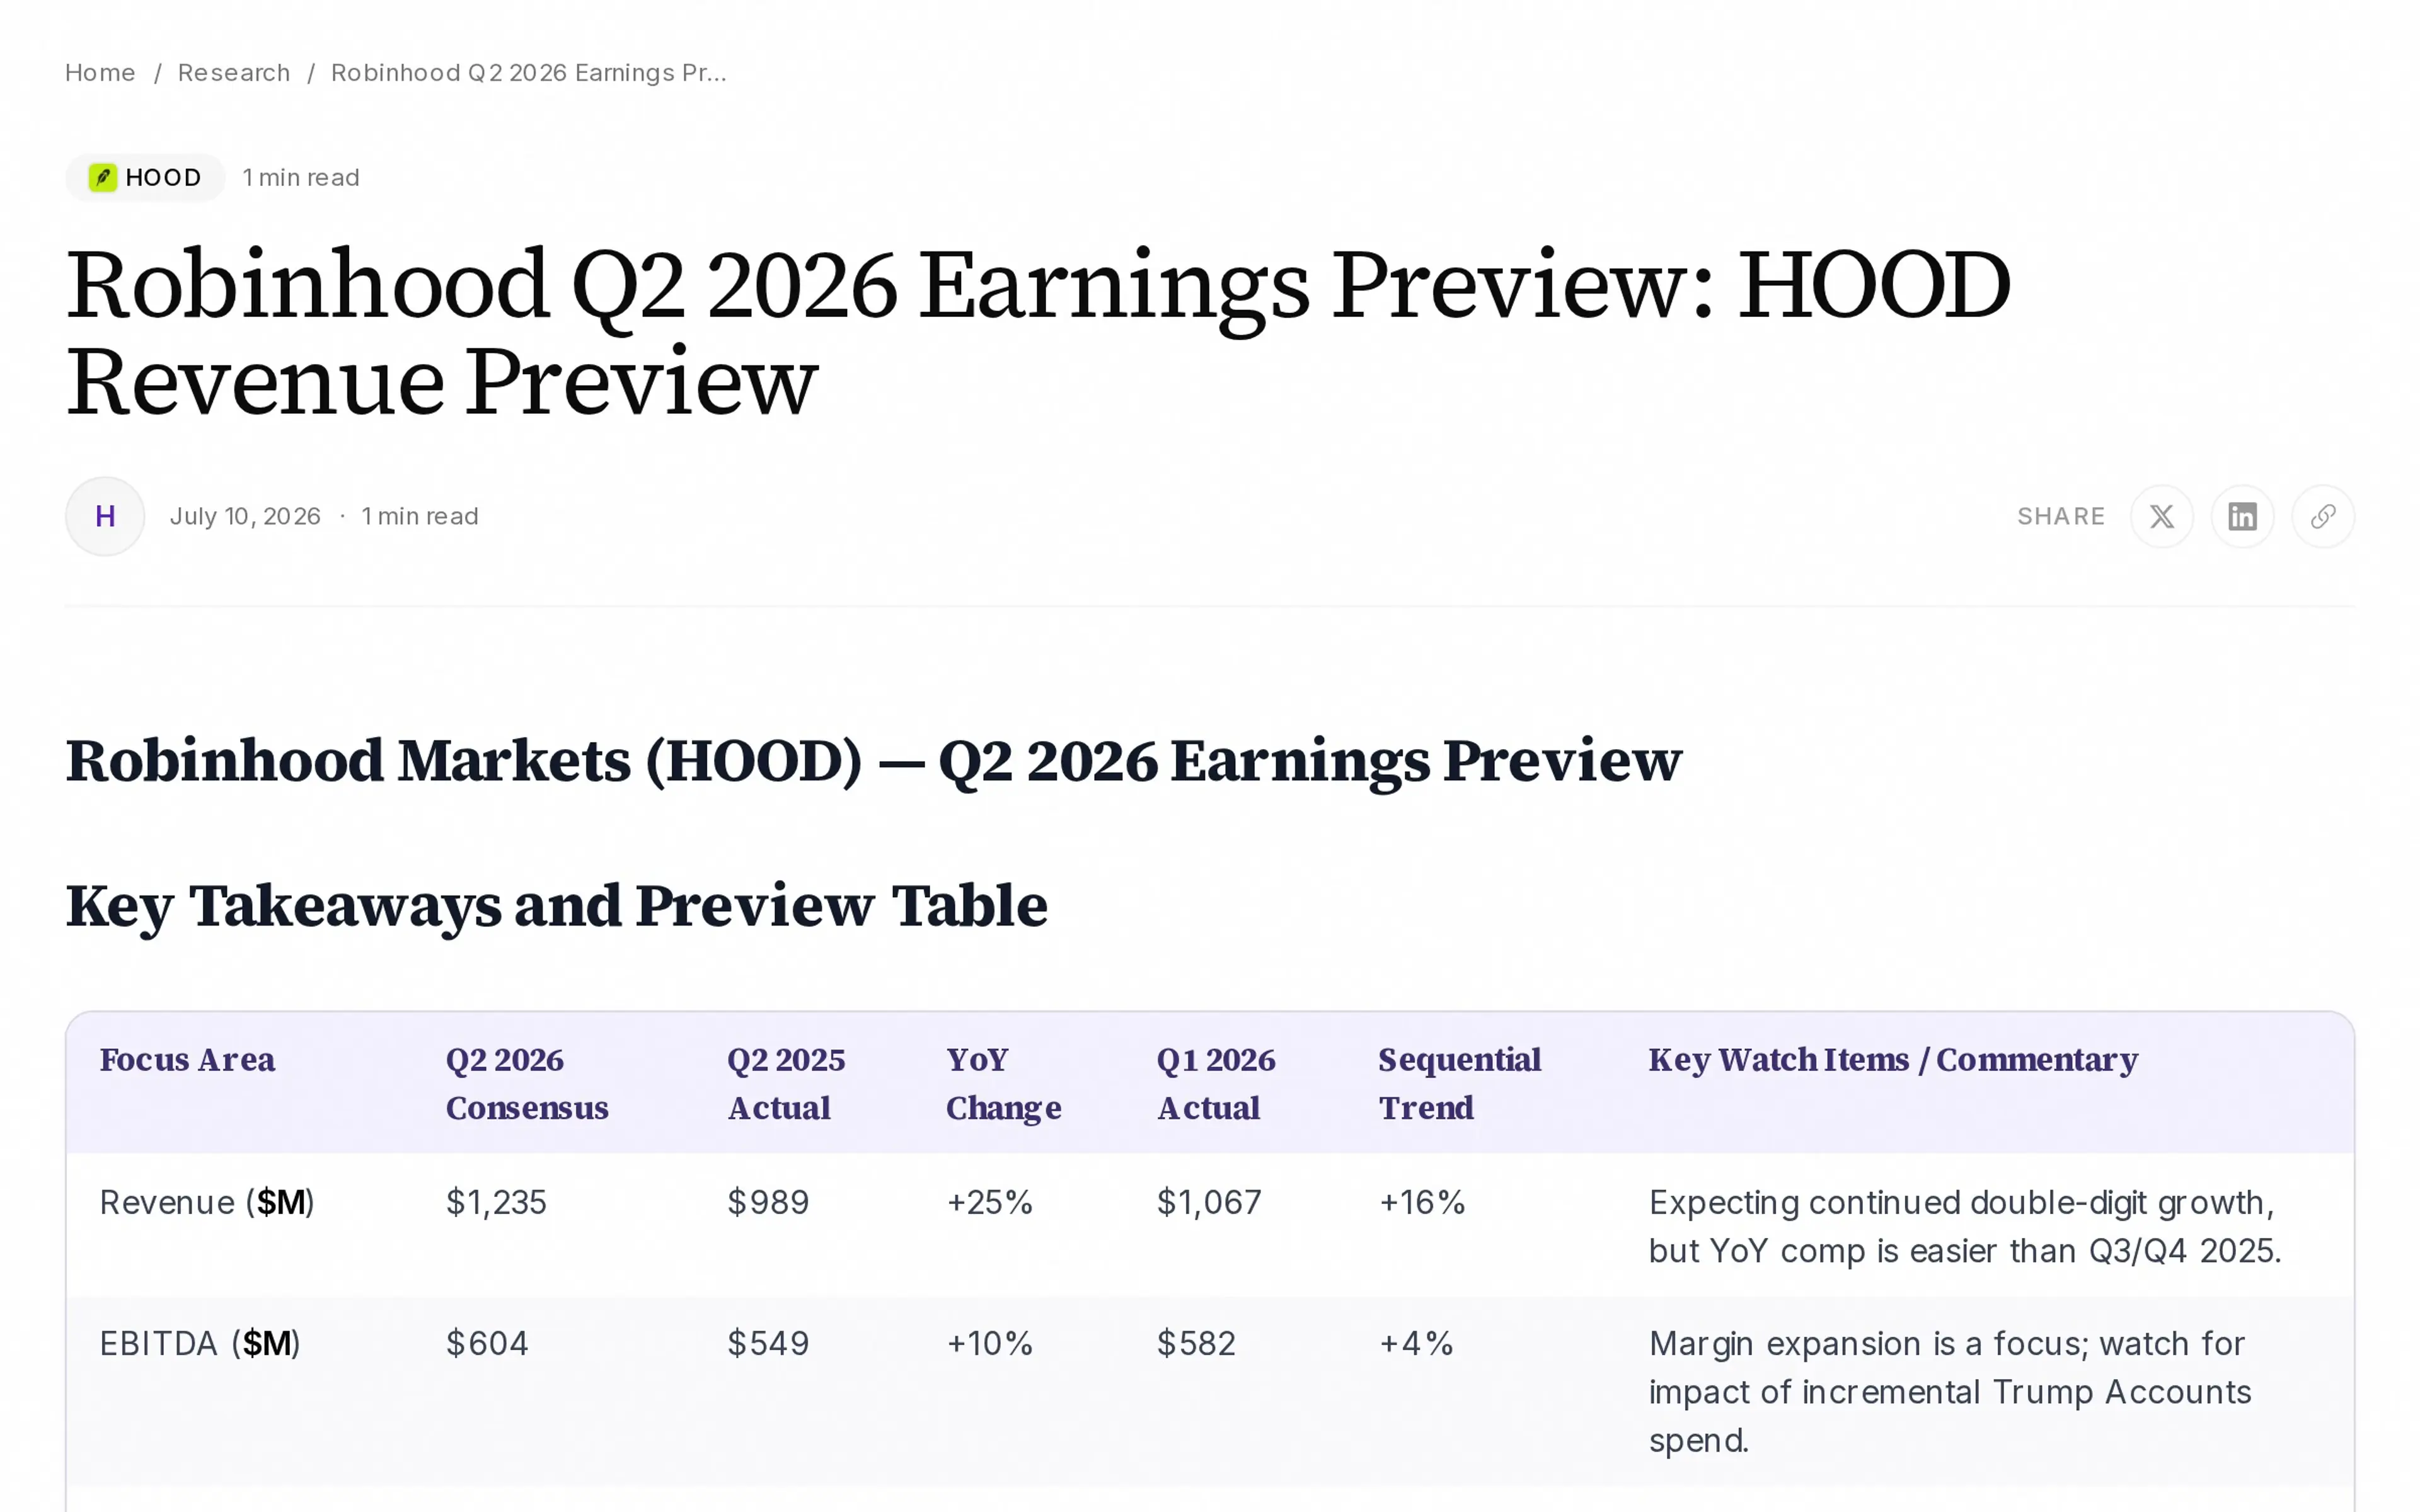
Robinhood Markets (HOOD) — Q3 2026 Earnings Preview
Key Points
| Factor | Details |
|---|---|
| Consensus Q3 2026 Revenue | $1,410M (+16% YoY vs. $1,215M Q3 2025 actual) |
| Consensus Q3 2026 EBITDA | $772M (+4% YoY vs. $741M Q3 2025 actual) |
| Consensus Q3 2026 EPS | $0.54 (+0.5% YoY vs. $0.54 Q3 2025 actual) |
| Q2 2026 Actuals | Revenue $1,281M (+5% QoQ, +32% YoY), EBITDA $630M, Net Income $390M, EPS $0.43 |
| Q3 2025 Actuals | Revenue $1,215M, EBITDA $741M, Net Income $559M, EPS $0.54 |
| Guidance | FY26 OpEx+SBC: $2.675B–$2.775B (lowered from prior), focus on self-funding new growth |
| Key Watch Areas | Net deposit growth (targeting 20%+ annualized), Gold subscriber attach rate, product velocity, traction in new products (Agentic Trading, Trump Accounts, Robinhood Chain), international expansion, take rates, and expense discipline |
Most Important Factors to Watch This Quarter
| Factor | Why It Matters |
|---|---|
| Revenue Growth | Consensus expects +16% YoY; Q2 saw +32% YoY, so the comp is not especially tough but growth is decelerating. |
| Net Deposit Growth | Management targets 20%+ annualized; Q2 was $22B (+28% annualized), July tracking at ~$4B (seasonally slower). |
| Gold Subscribers | Attach rate at 17% of funded accounts in Q2; strong driver of ARPU and cross-sell. |
| Product Velocity | Multiple new launches (Agentic Trading, Robinhood Chain, Trump Accounts); need to see continued adoption. |
| Take Rates | Q2 take rates stable QoQ; watch for mix shift (active vs. casual traders) and impact on revenue yield. |
| Expense Discipline | FY26 OpEx+SBC guidance lowered; margin expansion and self-funding of new initiatives are key. |
| International Expansion | Over 1M funded accounts ex-US; Singapore license, WonderFi/Indonesia ramp, Robinhood Chain global traction. |
| Trump Accounts | 7M children signed up, $1.5B+ in contributions; watch for ongoing engagement and cross-sell potential. |
| Agentic Trading/AI Products | Early adoption (100k+ accounts opened); roadmap includes broader asset access and easier UX. |
Quarterly Financial Snapshot — Actuals and Consensus
Quarterly Results and Estimates ($M except EPS)
| Quarter | Revenue | YoY Growth | EBITDA | Net Income | EPS |
|---|---|---|---|---|---|
| Q3 2026E | 1,410 | +16% | 772 | 596 | 0.54 |
| Q2 2026A | 1,281 | +32% | 630 | 390 | 0.43 |
| Q1 2026A | 1,136 | +15% | 582 | 354 | 0.39 |
| Q4 2025A | 1,341 | +27% | 832 | 645 | 0.64 |
| Q3 2025A | 1,215 | +33% | 741 | 559 | 0.54 |
*Consensus figures for Q3 2026; actuals for prior quarters.
Full-Year Financials — Actuals and Consensus
| Fiscal Year | Revenue | YoY Growth | EBITDA | Net Income | EPS | Cash Flow/Share |
|---|---|---|---|---|---|---|
| 2026E | 5,275 | +17% | 2,846 | 2,335 | 2.15 | 3.56 |
| 2025A | 4,529 | +59% | 2,558 | 2,148 | 2.04 | 2.85 |
| 2024A | 2,856 | 1,364 | 1,207 | 0.98 |
How Did They Report Last Year? (Q3 2025)
- Revenue: $1,215M (+33% YoY)
- EBITDA: $741M
- Net Income: $559M
- EPS: $0.54
- Net Deposits: $20B+
- Gold Subscribers: 3.9M (14% attach rate)
- Commentary: Record trading volumes, strong product velocity, diversification into prediction markets and Bitstamp, robust net deposit growth, and margin expansion.
Q3 2025 was a strong quarter with high growth rates and record KPIs, but the YoY comp for Q3 2026 is not unusually difficult given continued product launches and secular tailwinds.
Guidance and Management Commentary
FY26 Expense Guidance (as of Q2 2026)
| Metric | Guidance Range ($M) | Notes |
|---|---|---|
| Adjusted OpEx + SBC | 2,675 – 2,775 | Lowered and tightened from prior range; reflects self-funding of Rothera and WonderFi costs |
- Management continues to target 20%+ annualized net deposit growth.
- Focus remains on profitable growth: "We are still a growth company... able to self-fund a lot of these [growth initiatives]."
- Margin discipline: Q2 2026 adjusted EBITDA margin was 57%.
- Top KPIs: Net deposits, Rule of 40 (double-digit revenue growth + strong margins), number of $100M ARR businesses (now 13).
Intra-Quarter and Recent Conference Commentary
- July 2026 Trends: Average daily volumes for equities, options, and event contracts similar to Q2; net deposits tracking ~$4B (seasonally slower).
- Product Launches: Agentic Trading (AI agents for trading) now live for equities, options, crypto; over 100k accounts opened. Roadmap includes all asset classes and easier UX.
- Trump Accounts: 7M children signed up, $1.5B+ in contributions; employer and philanthropic flows ramping.
- Robinhood Chain: Over $12B DEX volume post-launch, fastest chain to 100M transactions, 120+ countries live, 200+ stock tokens available.
- International: Singapore license, WonderFi (Canada) closed, Indonesia brokerage live; strategy is to launch more complete product suites at once in new markets.
- Take Rates: Stable in Q2 and July; crypto slightly slower in July, but overall engagement healthy.
- Expense Discipline: Self-funding new initiatives, savings across M&A, core business, and new seeds.
Summary and Conclusions
- Q3 2026 Preview: Expectation is for continued double-digit revenue growth (+16% YoY consensus), strong profitability, and robust net deposit growth (targeting 20%+ annualized). The YoY comp is not unusually tough, but growth is decelerating from the very high rates of 2025.
- Key Watch Areas: Net deposit growth, Gold subscriber attach rate, adoption of new products (Agentic Trading, Trump Accounts, Robinhood Chain), international expansion, and expense discipline.
- Risks: Macro volatility, regulatory developments (especially for prediction markets and tokenization), and execution risk in scaling new products and international markets.
- Conclusion: Robinhood enters Q3 2026 with strong momentum, diversified growth vectors, and disciplined cost management. The most important factors for the upcoming report will be sustaining net deposit growth, demonstrating traction in new product launches, maintaining margin discipline, and showing progress in international and DeFi initiatives.
Upcoming Catalysts
- Q3 2026 earnings release
- HOOD Summit (active trader event, Houston, TX)
- Further rollout of Agentic Trading and Robinhood Chain features
- Expansion of Trump Accounts and employer/philanthropic contributions
- Additional international launches (Singapore, Indonesia, further Chain expansion)
In summary: Robinhood is coming off a period of strong growth and innovation, with Q3 2026 expected to show continued top-line expansion, robust customer engagement, and disciplined expense management. The company is not facing an unusually tough YoY comp, but investors should focus on net deposit growth, product adoption, and the ability to self-fund new initiatives while maintaining profitability.